Rule of 40
The Rule of 40 says a SaaS company's revenue growth rate plus its profit margin should total at least 40%. How to calculate it, which margin to use, and when it matters for small SaaS.
The Rule of 40 says a software company's revenue growth rate plus its profit margin should add up to at least 40%. Grow 30% with a 10% margin and you pass; grow 60% while losing 20% and you also pass; grow 15% with a 15% margin and you don't.
Rule of 40 calculator
Add your revenue growth rate and profit margin to see whether you pass the Rule of 40.
Rule of 40 score
45
Passes: growth plus margin is 40 or more.
- Points to 40
- 0
Use the same profit measure every time you compare. Free cash flow margin is the most common choice.
It is a quick check on whether a company is balancing growth and profit. Investors like it because it compresses two numbers that usually pull against each other into one. This guide covers where it came from, which numbers to plug in, how much it tells a small or bootstrapped SaaS (less than you might think), and what investors and founders have said about it in 2026.
Where the rule came from
The rule entered public writing in February 2015. Brad Feld wrote that he had heard it from a late-stage investor at a board meeting, as "the 40% rule for a healthy software company". Fred Wilson was at the same meeting and posted his own version a week later. Neither named an inventor. Feld's original post was about SaaS companies at scale, "assume at least $50 million in revenue", although he added that his own rule of thumb lined up with it from about $1 million of MRR.
Bessemer Venture Partners later adopted and spread the idea; it describes the Rule of 40 as a metric it "helped popularize". Bessemer also calls it the "efficiency score" in its benchmarks.
How to calculate it
The arithmetic is simple. Choosing the inputs is the hard part, and different sources use different ones.
Growth
- Feld: year-over-year growth in MRR, which he calls the "easiest / cleanest", checked against total revenue so one-off services income doesn't distort it.
- Wilson: annual revenue growth rate.
- Bessemer: year-over-year ARR growth rate.
- Public company dashboards such as Jamin Ball's Clouded Judgement show revenue growth for both the last twelve months and the next twelve months (forecast).
Profit
This is where scores diverge. Feld uses EBITDA as the baseline and backtests against operating income, net income and free cash flow. Wilson's version uses operating margin. Bessemer and Clouded Judgement use free cash flow margin. Any of these is defensible. Mixing them across quarters, or comparing your EBITDA-based score with someone else's FCF-based one, is not.
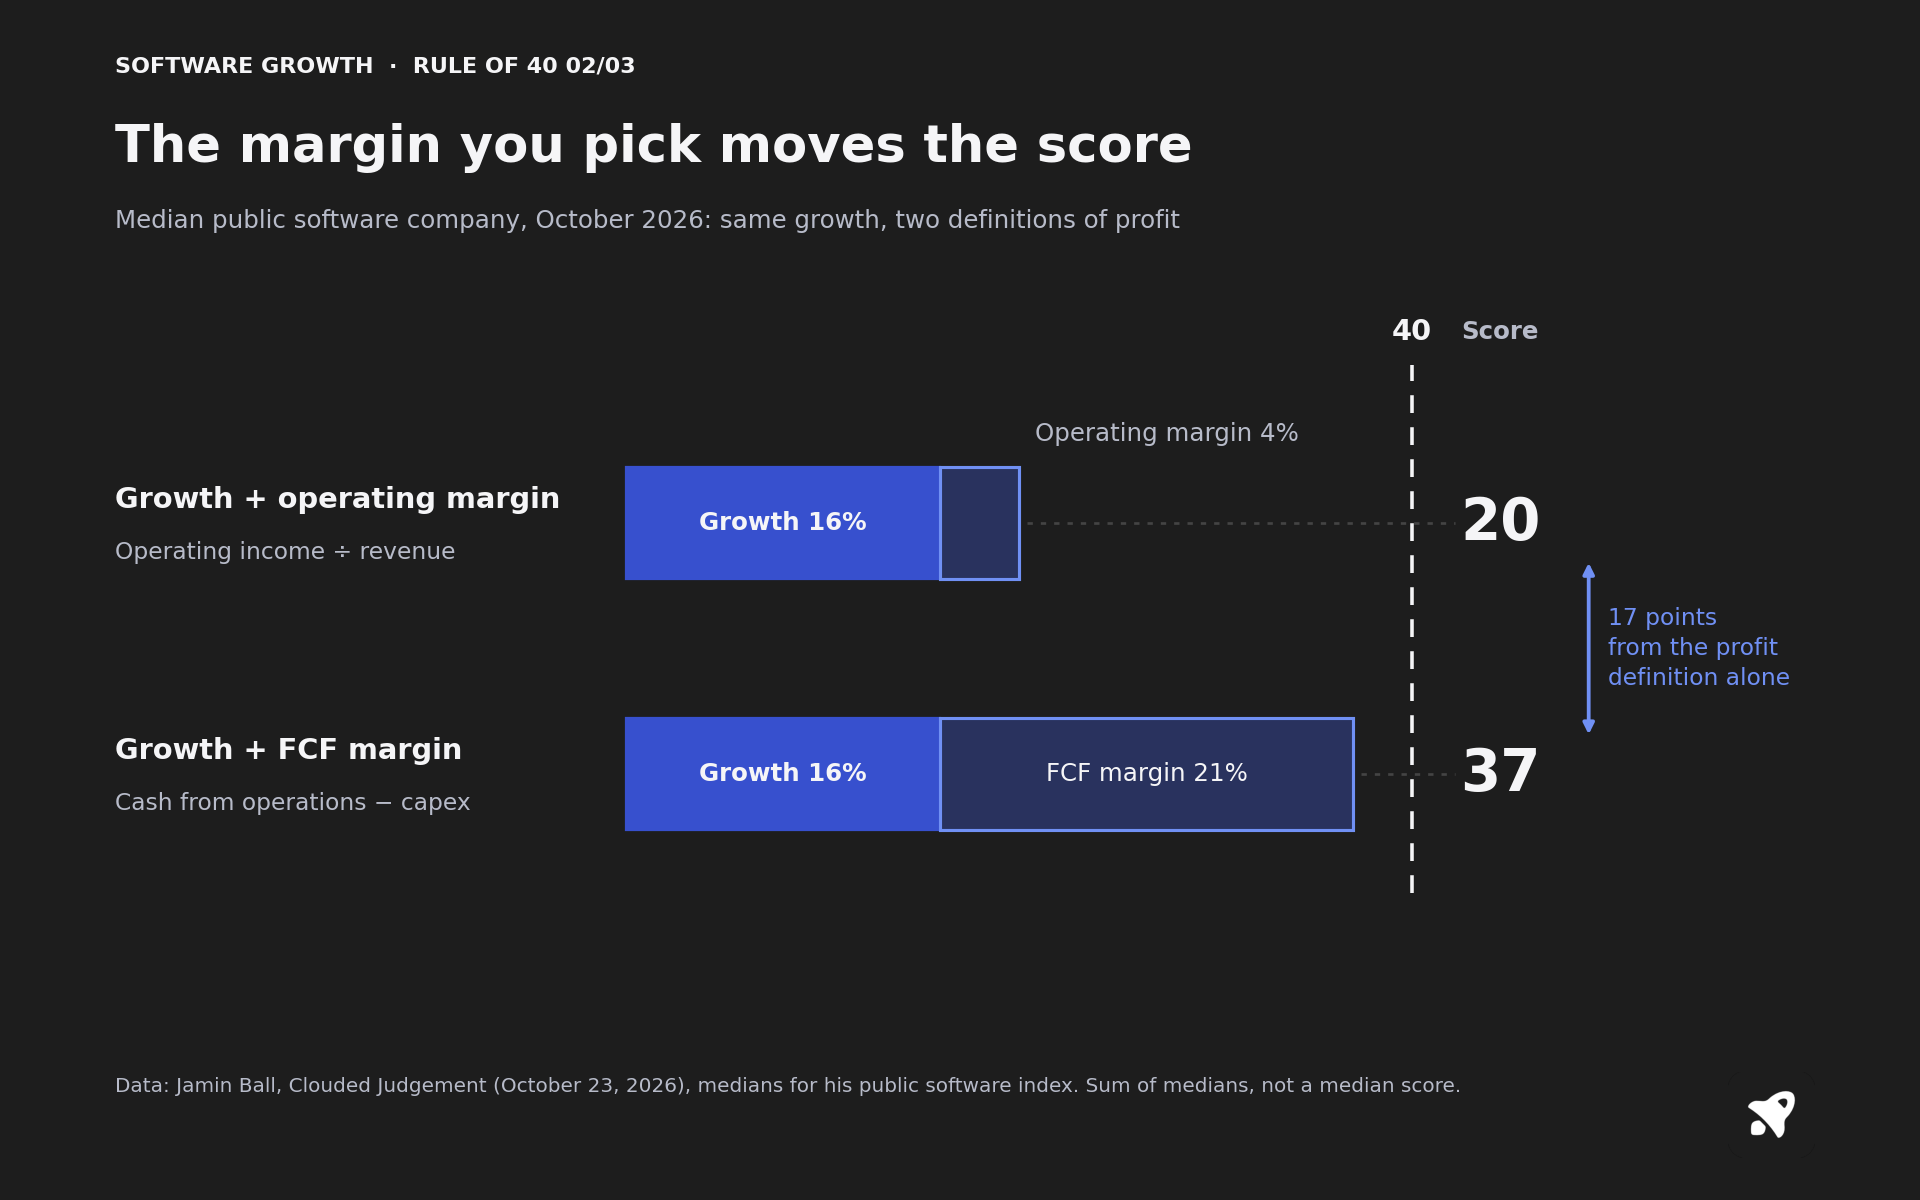
The gap can be large. In Jamin Ball's October 23, 2026 Clouded Judgement, the median public software company grew 16% over the last twelve months, with a median operating margin of 4% and a median FCF margin of 21%. Adding growth to each margin gives 20 or 37, a 17-point swing from the profit definition alone. Two common reasons free cash flow runs ahead of operating income in SaaS: customers who prepay annual plans bring cash in early, and stock-based pay counts as an expense in operating income without using cash.
The rule for your own business: pick one growth measure and one margin measure, write them down next to the score, and keep them fixed.
Worked examples
All the companies below are fictional. Growth is year-over-year ARR growth; margin is free cash flow margin.
- A steady small SaaS: ARR went from $1.0 million to $1.3 million, so growth is 30%. It produced $130,000 of free cash flow on $1.15 million of revenue in the year, a margin of about 11%. Score: 30 + 11 = 41. It passes.
- A venture-funded SaaS: growth of 60% with a margin of −20%. Score: 60 + (−20) = 40. It also passes, because the rule lets heavy growth spending offset losses.
- A profitable but slow SaaS: growth of 15% with a 15% margin. Score: 15 + 15 = 30. It fails, even though it makes money.
- A shrinking SaaS: Wilson's version spells this out. A company whose revenue is falling 10% a year needs a 50% operating margin to score 40.
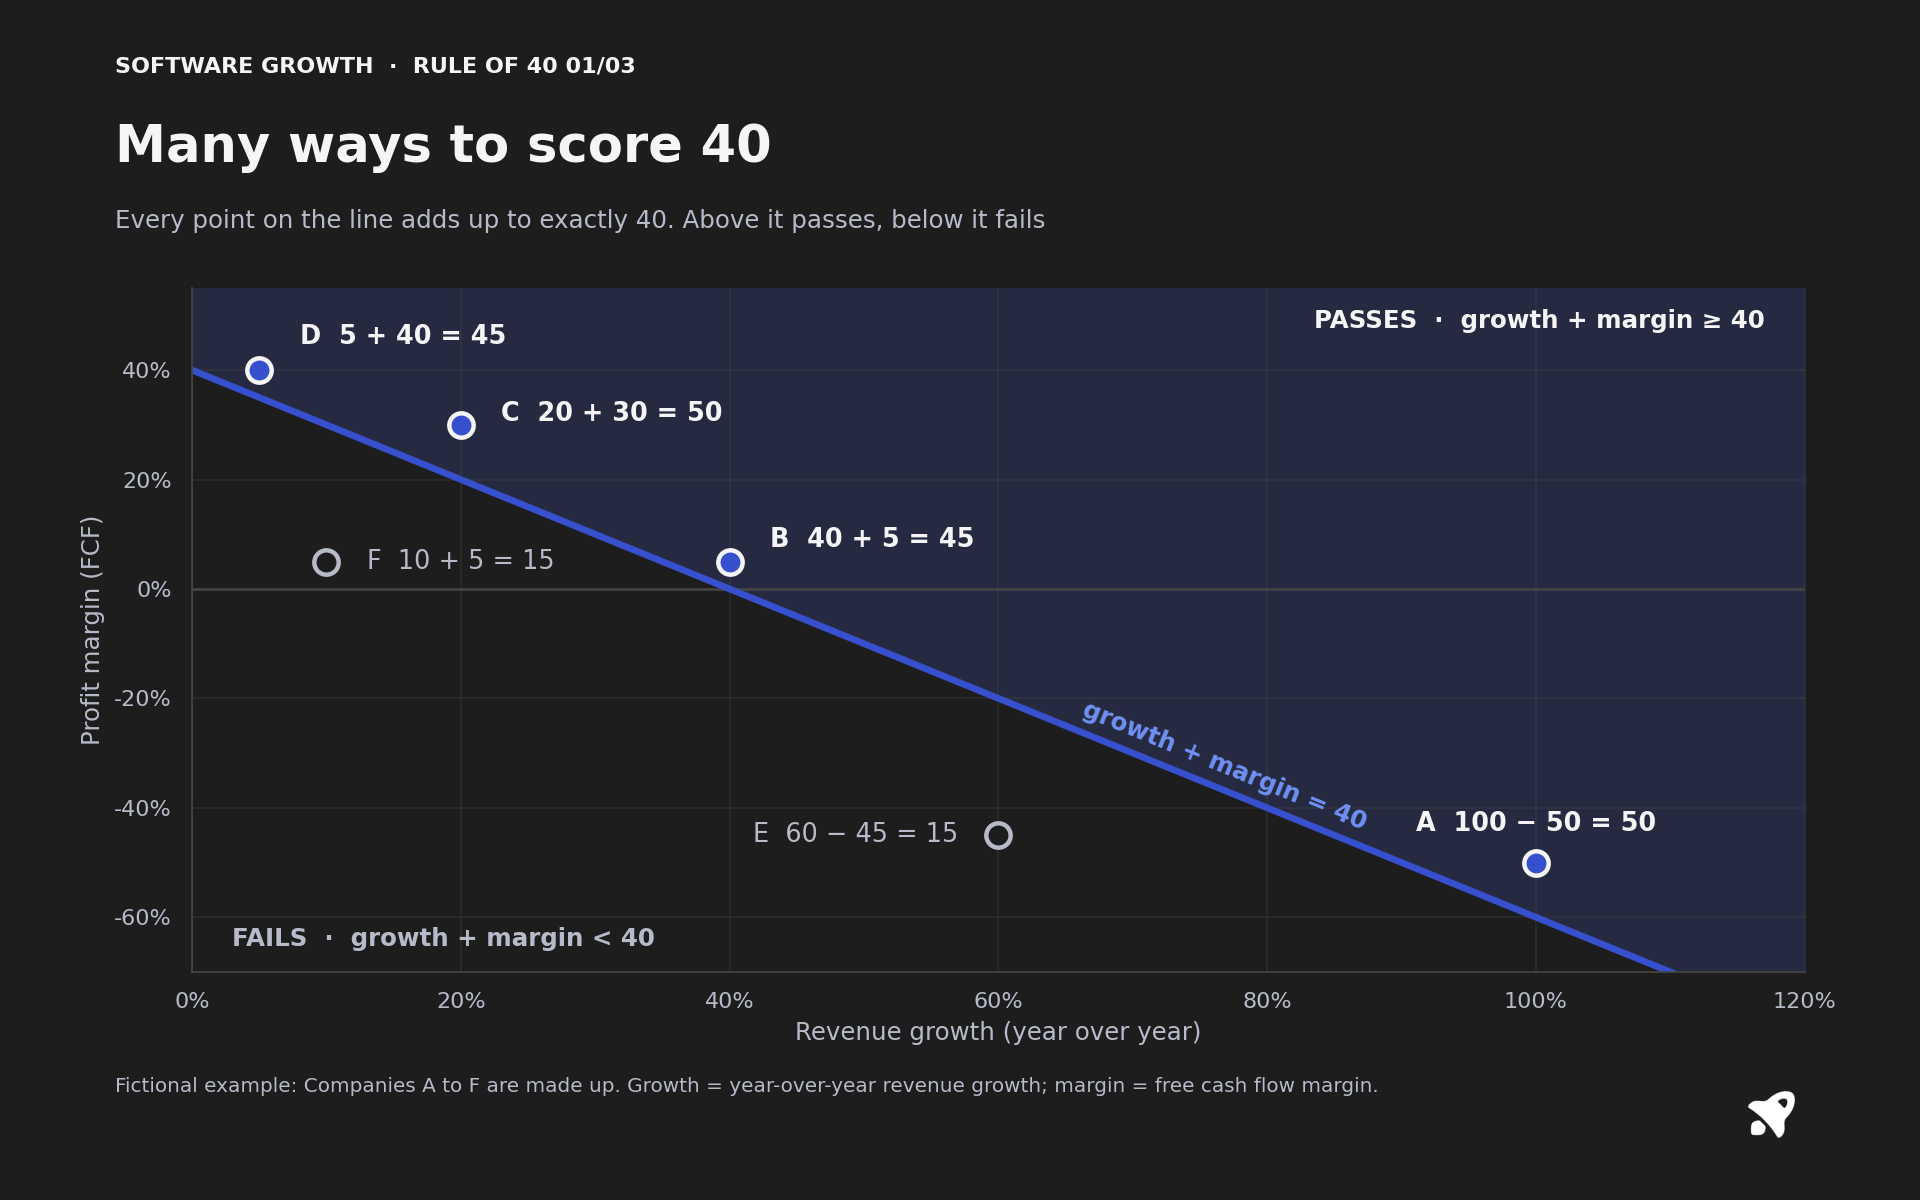
The chart shows the main idea: a company can pass from almost anywhere on the growth/margin map, and the two failing companies fail for opposite reasons. E spends heavily without enough growth to show for it. F is profitable, but its margin is too thin for its growth rate.
The growth-versus-margin trade-off
The rule treats one point of growth as worth exactly one point of margin. Bessemer's Byron Deeter and Sam Bondy argue that this is wrong once a company nears breakeven, because growth compounds and margin does not.
The traditional Rule of 40 math is dead wrong.
Byron Deeter and Sam Bondy / The Rule of X, Bessemer Venture Partners (January 2, 2024)
Their alternative, the Rule of X, multiplies growth by a factor, suggesting 2x to 3x in normal markets, before adding FCF margin. A company growing 30% with a 15% margin scores 45 on the Rule of 40 but 75 on the Rule of X with a 2x multiplier (30 × 2 + 15). Bessemer reports that the Rule of X correlates more strongly with public valuation multiples. Bessemer itself warns that it is less useful for early companies with heavy burn, where it points to the burn multiple instead.
Recent market data points the same way. Summarizing Kroll's Summer 2026 software sector update, Jason Lemkin noted (August 29, 2026) that median public revenue multiples rose from 2.4x for shrinking companies to 7.2x for those growing above 20%, while median EBITDA margins were roughly flat across those groups, between about 25% and 32%. He also found categories with identical Rule of 40 scores trading far apart: engineering software and HR software both scored 46%, at 5.2x and 3.0x revenue. His advice: stop pushing margin past about 25% and put the money into growth.
In practice, the Rule of 40 is a floor, and the mix behind the score matters as much as the sum.
What good looks like
- Public cloud companies, late 2023: Bessemer put the average Rule of 40 for its cloud index at about 31%, with the top decile at about 48%.
- Public software, October 2026: using Clouded Judgement's medians (16% trailing growth, 21% FCF margin), a typical public company lands in the high 30s, just under the line.
- Scaling private companies: Bessemer's Scaling to $100 Million treats the score as meaningful only after about $25 million of ARR, and encourages its portfolio to target 70% between $25 million and $50 million of ARR, and 50% at $100 million and above.
- Private B2B SaaS: SaaS Capital's 2025 survey analysis found that the median bootstrapped company outscored the median equity-backed one, but the gap was narrowing, and scores fell for almost every group between 2023 and 2025, mostly because growth slowed.
Bootstrapped and small SaaS: how much it applies
Less than the attention it gets would suggest. Feld wrote it for $50 million companies and Bessemer for $25 million and up. For a small or bootstrapped SaaS, three things distort the score:
- A small base inflates growth. Going from $50,000 to $120,000 ARR is 140% growth. That number won't last, and a score built on it says little about the business.
- Founder pay distorts the margin. If the founder takes a below-market salary, or pays themselves through distributions instead of payroll, the margin looks better than the business really is. Before you compare, deduct a market salary for the work you do.
- Annual prepayments flatter cash flow. A push to annual plans can lift FCF margin for a year without changing the underlying business.
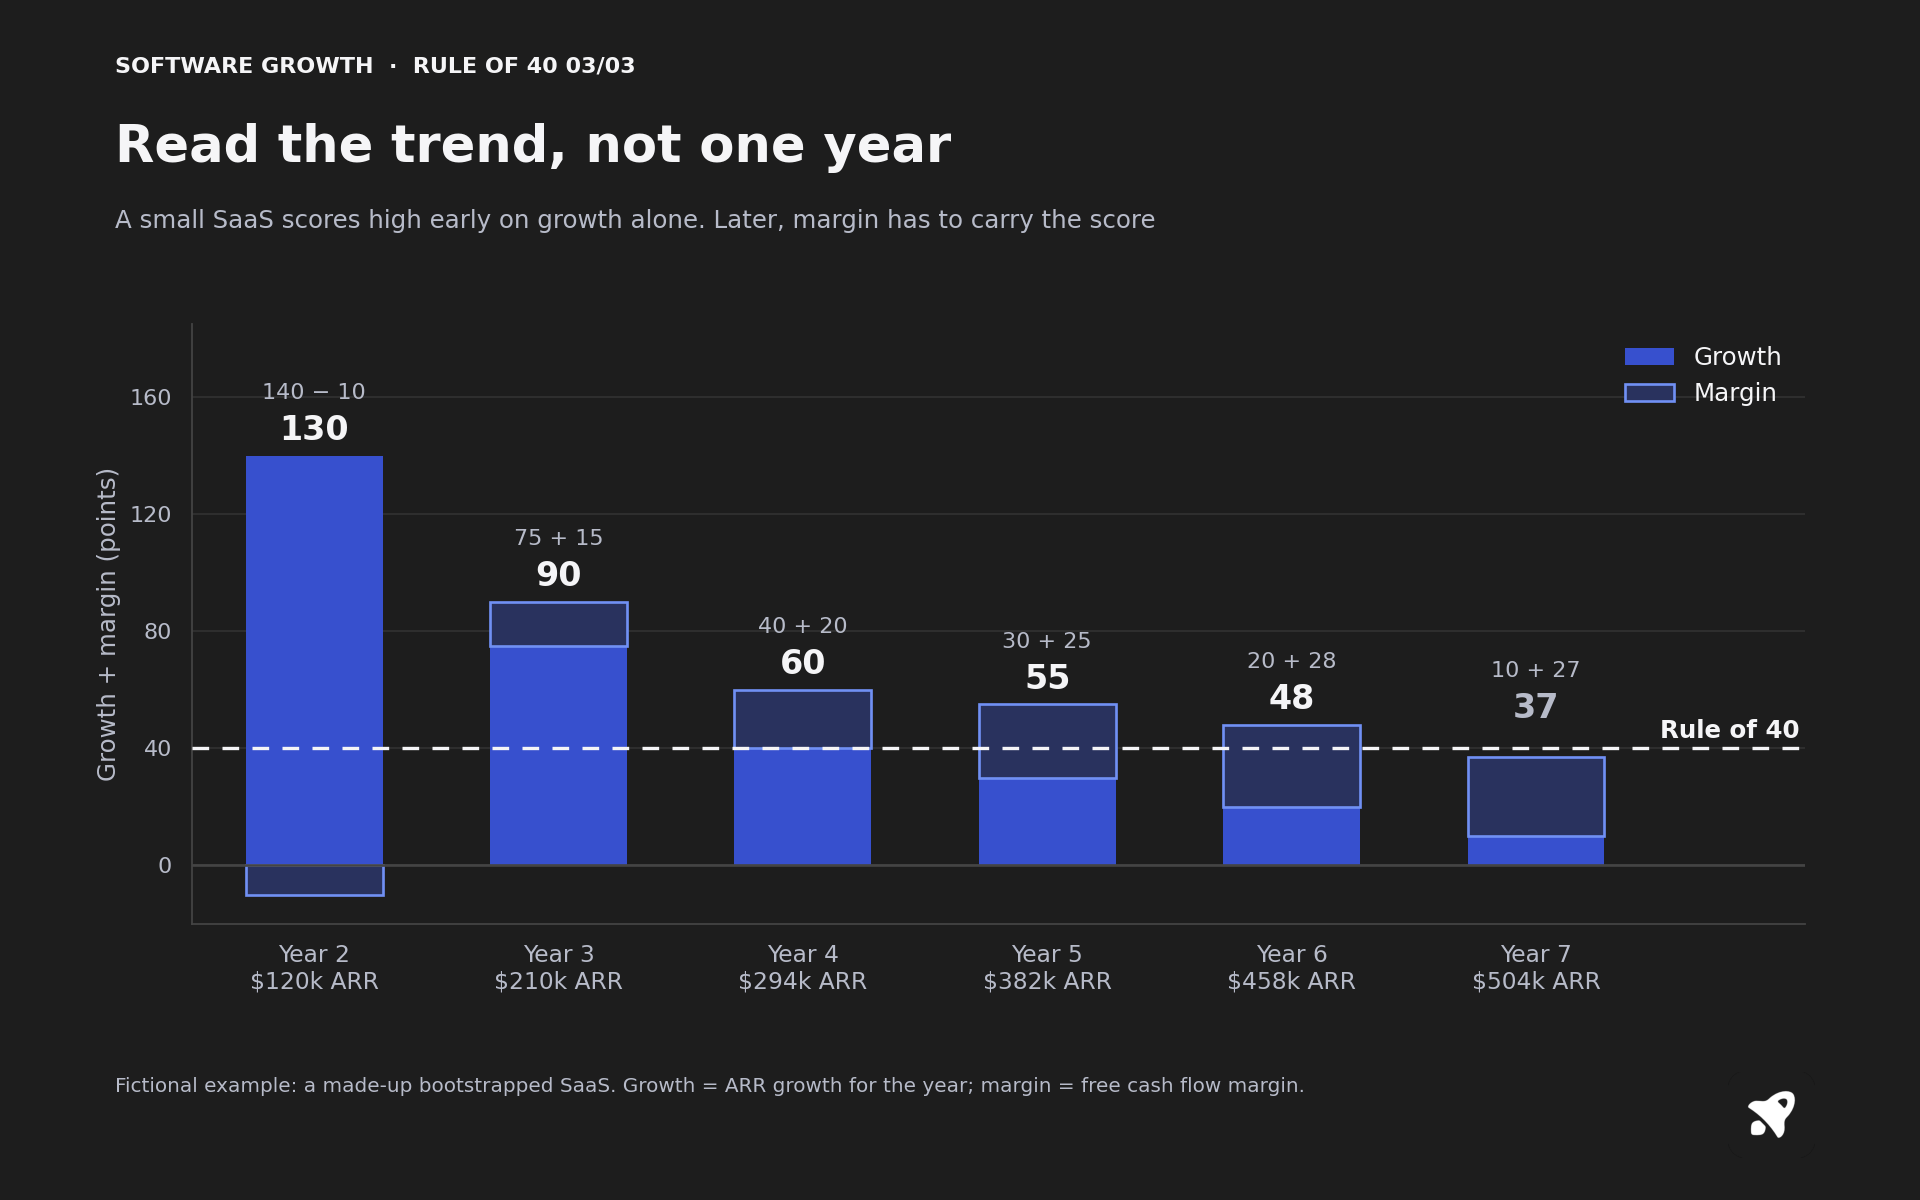
The useful question for a small company is the direction of the trend. In the fictional example above, the score drops from 130 to 37 as growth slows, even though the margin keeps improving. Year 7 fails, but the business is healthier than it was in year 2. What matters is whether growth is decaying faster than margin can make up for it, and whether that leaves you with a business you want to own.
Feld made a related point in 2015: sub-scale companies that slow growth to get profitable "will end up being sub-scale for a much longer time". That's a real cost if you plan to raise money or sell. If you're building a business to own and run, a 20% growth rate with a 30% margin is a fine outcome. For a bootstrapper, being default alive matters more than any benchmark.
What changed in 2026
Read the curve, not the snapshot
In June 2026 Feld returned to the rule in Does the Rule of 40 Work for Hardware? He still likes it, but argues that a single period can mislead. Young hardware companies often fail it for years while doing everything right. His fix is to watch the trajectory of margins and growth.
The market rewards growth until it doesn’t, and then it rewards profitability.
Brad Feld / Does the Rule of 40 Work for Hardware? (June 15, 2026)
Investors in public software apply the same idea. In his September 17, 2026 analysis of ServiceTitan, Lemkin worked out that its guidance put the second half of the year at a Rule of 40 of about 27, down from 36 in the quarter just reported and 37 a year earlier. The stock fell 30% in a day, even though the full-year revenue guidance went up.
The market has been trading the slope, not the total.
Jason Lemkin / 5 Interesting Learnings from ServiceTitan, SaaStr (September 17, 2026)
Margins are table stakes
The Kroll data Lemkin covered in August suggests that public investors now treat a 25% to 30% EBITDA margin as normal, and pay for growth above that. That favours companies that can still grow 20% or more, and makes a high score built mostly on margin worth less than the same score built on growth.
The AI era stretches both ends
AI has made extreme scores possible. Lemkin reported Palantir's Rule of 40 at 155% (August 4, 2026), from 93% growth and a 62% adjusted operating margin. Its GAAP operating margin was 47%, which would give 140. The headline score depends on the margin measure here too.
AI can also squeeze the margin side. Tomasz Tunguz's reading of Anthropic's S-1 (October 26, 2026) derives a gross margin of about 40% for 2025, his own calculation, alongside 11.9-fold growth. Compare that with the 76% median gross margin for public software in Jamin Ball's October 23 Clouded Judgement. For small SaaS companies adding AI features, Rob Walling raised the same issue:
…they could be very expensive and they could hit your profit margin.
Rob Walling / Startups for the Rest of Us, episode 847 (August 25, 2026)
He was talking about AI agents. His point: you might charge ten times a seat price for an agent and still earn the same net profit as before. If you add inference-heavy features, recalculate your margin with the real model costs before you count on the price increase to lift your score.
Using it as a decision tool
The rule works best as a way to frame a trade-off. If your score is 30 and you want 40, you have two levers: grow faster or earn more. Decide which is cheaper for you. A product with sticky customers and strong net revenue retention may find it easier to raise prices and lift margin. A product in a fast-moving market may be better off spending more on growth, as long as the magic number and burn multiple show that spending converts into revenue. Track the score every quarter on the same definitions, and look at the direction over several quarters, not one result.
Common mistakes
- Switching profit measures between periods, or comparing your EBITDA-based score with a benchmark built on free cash flow.
- Treating a high score at $100,000 ARR as proof of anything. Very high growth rates on a small base don't last.
- Counting a below-market founder salary as profit.
- Cutting growth investment to hit 40, when the market data says margin above about 25% earns little extra.
- Reading one quarter in isolation instead of the trend over several quarters.
- Using it to judge an early-stage company with heavy burn, where the burn multiple and runway tell you more.
Listen, watch and read next
- Read: Does the Rule of 40 Work for Hardware?, Brad Feld (June 15, 2026). The person who first blogged the rule on why the trend matters more than any single period.
- Read: The Rule of X, Byron Deeter and Sam Bondy, Bessemer Venture Partners. The strongest argument for weighting growth above margin, with benchmarks.
- Read: Growth, Profitability, and the "Rule of 40" for Private SaaS Companies, SaaS Capital (August 21, 2025). Private-company data that splits bootstrapped from equity-backed firms.
- Read: Rule of 40 Is Half Dead, Jason Lemkin (August 29, 2026). What 2026 M&A and public market data say about growth versus margin.
- Listen: Startups for the Rest of Us, episode 847, Rob Walling (August 25, 2026). Includes how to price AI agents and why their costs can eat into margin.
- Watch: The SaaS Rule of 40: How to Calculate and Why It Matters, The SaaS CFO. A walkthrough of the calculation from a SaaS finance channel.
Related terms
- Burn multiple
- EBITDA
- Free cash flow
- Operating margin
- ARR growth rate
- SaaS magic number
- Default alive
- ARR (Annual recurring revenue)
Sources
- The Rule of 40% for a Healthy SaaS Company, Brad Feld, February 3, 2015
- The 40% Rule, Fred Wilson, AVC, February 10, 2015
- Does the Rule of 40 Work for Hardware?, Brad Feld, June 15, 2026
- The Rule of X, Byron Deeter and Sam Bondy, Bessemer Venture Partners, January 2, 2024
- Scaling to $100 Million, Bessemer Venture Partners, September 21, 2021
- Growth, Profitability, and the "Rule of 40" for Private SaaS Companies, SaaS Capital, August 21, 2025
- Clouded Judgement 10.23.26, Jamin Ball, October 23, 2026
- Rule of 40 Is Half Dead, Jason Lemkin, SaaStr, August 29, 2026
- 5 Interesting Learnings from ServiceTitan at $1.14 Billion in Revenue, Jason Lemkin, SaaStr, September 17, 2026
- 5 Interesting Learnings from Palantir at $7.7 Billion ARR, Jason Lemkin, SaaStr, August 4, 2026
- Anthropic S-1 Analysis: How 7 Key Metrics Stack Up, Tomasz Tunguz, October 26, 2026
- Episode 847, Rob Walling, Startups for the Rest of Us, August 25, 2026